+31(0)884321800
 en
 nl

Mandatory eInvoicing and eReporting from 1 July 2028
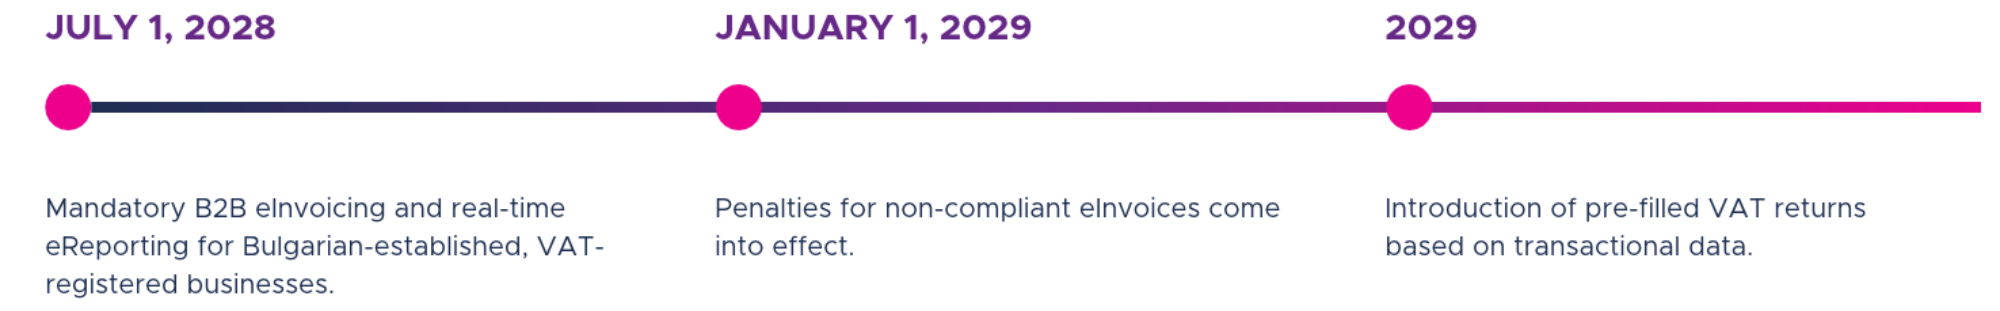
Bulgarian-established and VAT-registered businesses would be required to issue structured electronic invoices for most domestic B2B transactions. Electronic invoices would need to be exchanged either through approved eInvoicing networks or via a national portal operated by the National Revenue Agency (NRA). Businesses could issue invoices directly through the national platform or through their own invoicing software. Where their own systems are used, the invoice data would have to be transmitted to the NRA in real time.
Reverse-charge mechanism expands from July 2028
From July 2028, where a supplier is VAT-registered in Bulgaria but not established there, the Bulgarian VAT-registered customer would generally become responsible for accounting for the VAT. This rule would apply broadly rather than being limited to specific transaction types.
New penalties from 1 January 2029
Financial penalties would be updated and expanded. Specific sanctions would apply to businesses that fail to issue compliant structured eInvoices. Enforcement of these penalties would begin only from 1 January 2029, providing a transition period.
Pre-filled VAT return from 2029
Under the proposal, transactional data would be used by the NRA to pre-fill VAT returns from 2029.
If your organization operates in Bulgaria, review your ERP, accounting and invoicing systems now to assess the impact of these changes. Businesses not established in Bulgaria but holding a Bulgarian VAT registration should pay particular attention to the proposed reverse-charge rules. Bulgarian customers may face additional obligations to self-account for VAT on certain transactions.
 2 min
Daniëlle van der Meulen-Idema
Sr. VAT & Tax Technology Specialist